A/R Deduction Recoverability by Age

Accounts receivable analyst reviewing deduction aging reports and SKU-level reconciliation data to identify recoverable overcharges.

Accounts Receivable deductions can dilute revenues from 5%  in industrial companies to 20% in consumer products companies. These deductions arise from various issues, including ordering and billing errors, returned merchandise, pricing discrepancies, trade promotion deals, payment discounts, shipping errors, and non-compliance with customer vendor policies.

Deduction overcharges, far from being exceptional, are a common occurrence. Many deductions contain errors that can significantly impact sellers’ profits. For instance, up to 50% of returns are overstated due to SKU, price, or quantity errors. Post-audit deductions, which result from post-payment reviews, can be over 75% incorrect. Errors in trade deals and volume discount deductions are often substantial. These inaccuracies underscore the need for efficient reconciliation and resolution processes to mitigate the potential for significant and sometimes hidden revenue and profit losses.

Reconciling deductions against related credit memos is challenging due to the volume and variety of SKUs. Our extensive experience and specialized software enable us to reconcile and identify overcharges on any scale, even spanning several years for a trading partner.

Deduction Staff and Systems

Other crucial factors in managing deductions include the experience of your staff and the time available to pursue these claims. The most effective A/R systems utilize automated bots to access claims from major retailers before deductions are made, allowing more time to resolve issues before automatic deductions occur. Some chain retailers even have time periods, say 60 days, after which they consider their claim valid and won’t discuss it. This underscores the need for a strategic approach to deduction management, considering both your staff’s capabilities and the process’s time constraints.

Twenty years ago, many deductions were “negotiable,” and 50/50 across-the-board settlements were sometimes possible. Today, you must prove the customer is wrong in specific detail and do it quickly. While most deductions are generally accurate, the average recoverability on gross deducted amounts ranges between 10% and 20%, depending on factors like your industry, customer base, processes, systems, and the speed of your investigation. There is a lot of money involved.

Information You Get from Analyzing Deductions

Analyzing customer Accounts Receivable (A/R) deductions can uncover various operational errors impacting a company’s financials and operations, so your systems should include root cause accountability, enabling you to eliminate systemic process failures. Here are some common types of operational errors that can be identified:

1. Pricing Errors

  • Incorrect Pricing: Not billing according to the P.O. terms.
  • Misapplied Discounts: Applying discounts incorrectly or not applying agreed-upon discounts.
  • Price Changes Not Updated: Customer failure to update systems with current pricing information.

2. Shipping and Delivery Errors

  • Incorrect Shipments: Using the wrong carrier, not calling for appointment windows.
  • Late Deliveries: Delivering products later than agreed, causing penalties.
  • Shipping Damage: Products damaged during shipping, leading to returns or deductions.
  • Freight Charges Errors: Incorrectly billed shipping and handling charges.

3. Compliance and Contractual Errors

  • Non-Compliance with Vendor Policies: Not adhering to customer’s specific vendor compliance requirements.
  • OTIF failures
  • Contractual Non-Compliance: Failing to meet terms and conditions stipulated in contracts.
  • EDI Errors: Issues related to Electronic Data Interchange, such as incorrect formats or missing data.

4. Trade Promotion and Discount Errors

  • Promotion Misapplication: Incorrectly applying trade promotions and discounts.
  • Unauthorized Deductions: Customers taking unauthorized deductions without proper agreement.
  • Rebate and Allowance Mismanagement: Errors in calculating or applying rebates and allowances.

5. Returns and Refund Errors

  • Misprocessed Returns: Incorrect processing of returned goods, leading to overstated returns.
  • Return Authorization Issues: Not properly authorizing returns, resulting in disputes and deductions.
  • Restocking Fee Misapplication: Failing to apply restocking fees where applicable.

6. Order Processing Errors

  • Order Entry Mistakes: Errors in entering orders into the system, leading to incorrect fulfillment.
  • Miscommunication: Issues stemming from poor communication between sales, billing, and shipping departments.

7. Inventory and Stock Management Errors

  • Stock-Out Situations: Failure to fulfill orders due to inventory shortages.
  • Overstock Situations: Accumulating excess inventory leading to potential obsolescence or markdowns.
  • Incorrect Stock Levels: Discrepancies between actual and system-recorded inventory levels.

8. Data Entry and System Errors

  • Manual Entry Errors: Mistakes in entering data manually, leading to inaccuracies.
  • System Integration Failures: Problems with the integration between different systems, causing data inconsistencies.
  • Outdated Information: Using outdated customer or product information in transactions.

By identifying and addressing these operational errors through A/R deductions analysis, companies can improve their processes, reduce revenue leakage, and enhance overall operational efficiency.

Lastly — Time is of the Essence to Recovery of Deduction Errors

The collectibility of deductions varies based on the type of claim, the systems and documentation you have, and the time it takes to complete your investigation and reconciliation.

A critical factor is the time it takes to research, reconcile, and prove overcharges, which often takes months, during which the likelihood of collectibility plummets. Deduction value depreciates far faster than invoice receivables so time is of the essence in tackling this challenge.

For instance, while an average overcharge rate of 14% might be assumed, this figure can be misleading. Some deductions may be entirely uncollectible (0%), while some may be fully recoverable (100%). The true nature of each deduction is only revealed through a thorough investigation.

This is where the value of intelligent automation and experienced deduction audit staff becomes evident. Automated A/R systems, like Smyyth’s advanced Carixa, for example, can cut the time it takes to document deductions from weeks to one or two days,  immensely increasing the collection rate of deduction errors. Professional staff with access to this type of software could produce ROI of 100% or more.

From the practitioners at Smyyth LLC
Collection Agency Should be Part of Your Collection Workflow

Accounts receivable workflow diagram showing internal collections escalating to third-party agency placement after 90 days past due.

All businesses face cash flow issues during challenging economic climates, making it especially difficult to collect customer payments within the agreed-upon terms. To optimize your collection efforts and cash flow, it is essential to reevaluate the priorities of your collection department, including the utilization of third-party collection agencies. Making timely referrals to these agencies for bad debts can significantly improve collection results while minimizing unnecessary costs.

Is Using an Agency a Collection Failure or an Integral Part of the Process?

  • Needing a collection agency does not represent your department’s collection failure, as a certain percentage of all customers are destined to fall into this category regardless of how hard to try to collect.
  • When your collector staff exhausts their efforts without yielding results, there comes the point of diminishing returns. In such cases, a timely collection referral can be a victory for your company.
  • Holding onto past-due accounts for extended periods diverts your staff’s attention from high-priority customers and balances, which are more profitable. Continuously pursuing payment from those who consistently fail to pay is an unproductive use of resources.
  • By allowing collection agencies to handle difficult cases, your internal collectors can focus on where the cash comes from rather than being tied up with long overdue unpaid balances. The longer an account remains past due, the more challenging it becomes to collect. Collectability decreases each month to the extent that after nine months, the likelihood of collection may be close to zero.

Important! Your past-due customers will seek other suppliers and you will lose business if you do not collect. Consequently, integrating timely collection agency referrals into your collection process is essential.

Considerations for Collection Agency Placements:

  1. Utilize your internal resources for accounts 10 to 90 days past due, as they contribute 95% of your cash flow and offer a high return on your time investment. Allow your staff to focus on the accounts receivable that keep your business running.
  2. Waiting beyond 90 to 120 days and hoping for collection before referring the account to a collection agency is counterproductive. Timely interventions are more likely to succeed.
  3. Assigning accounts to a collection agency immediately grabs customers’ attention as they realize that the unpaid debt could negatively affect their credit bureau scores.
  4. Collection agencies charge fees based only on the cash recovered, and a reputable agency increases the chances of successful collection.
  5. The agency can tailor their collection tactics, employing a customer service approach when you hope for future business and a more assertive approach for chronic late payers.

When is the Right Time to Refer a Debt for Collection?

Consider the following five factors before deciding to refer a customer to a collection agency:

  1. The account is 90 days late.
  2. The customer has failed to follow through, broken a promise to pay, or become difficult to reach.
  3. The customer has indicated financial difficulties.
  4. Remember that your customers prioritize their cash payments, and they pay those who have taken more aggressive actions or whose products they need. You have become a low priority and will lose future revenues if you do not collect.

What to Look for in a Collection Agency:

When selecting a collection agency, keep the following eight factors in mind:

  1. Membership in a professional organization such as the International Association of Commercial Collectors (IACC) upholds a strict code of ethics and legal compliance.
  2. Agencies specializing in either B2B or consumer collections. Collecting from businesses is more challenging and requires specialized expertise. If you have commercial debt, choose a commercial bad debt agency.
  3. A well-established track record, having been in business for many years.
  4. The ability to communicate with the agency’s management before initiating business and during the collection process. 
  5. An excellent history of collection results and adherence to market-standard contingency fees.
  6. Strong reviews, such as positive feedback from clients on platforms like Google, indicate trustworthy and quality relationships.


Machine Learning in Credit & Collection Scoring

Finance team using AI-driven accounts receivable software dashboard displaying predictive payment scoring and cash flow forecasts.

Managing receivables is a crucial aspect of B2B financial management. Late or unpaid invoices and bad debts can significantly impact cash flow, causing businesses to struggle to meet their financial obligations. Companies rely on various tools, including payment and credit scoring, to prioritize their B2B collection activities to stay on top of outstanding payments.

Payment history is an essential tool for managing B2B collections. It provides insight into customer behavior and can be used to prioritize collection efforts and focus on accounts most at risk of defaulting. For example, if a customer consistently pays late, it may be necessary to send reminders or follow up more frequently than with a customer who always pays on time.

Machine Learning (ML) is a branch of artificial intelligence that involves developing algorithms and models that enable computers to learn from data and make predictions or decisions without being explicitly programmed. In accounts receivable, machine learning is used to automate and optimize the remittance application process, the collections process, deduction validation, matching debits to credit memos, and cash forecasting.

Advanced accounts receivable management software often uses Machine Learning (ML) to analyze a wide range of data points, such as a customer’s payment history, credit score, industry, and geographic location. By combining this information with external data sources, such as economic indicators and market trends, ML algorithms can better predict a customer’s payment behavior. In addition, ML can automate many of the time-consuming and repetitive tasks involved in the AR collection process, such as sending reminders to customers, flagging overdue invoices, and prioritizing collection efforts.

6 Reasons to Use Machine Learning in AR Software

  1. Predicting Payment Behavior: ML algorithms can analyze historical data on customer payment behavior to identify patterns and predict when and how much a customer is likely to pay. This can help collections teams prioritize their efforts and focus on customers most likely to pay.
  2. Identifying High-Risk Accounts: ML algorithms can analyze a variety of factors, such as payment history, credit scores, and other financial data, to identify accounts that are at high risk of becoming delinquent. This can help collections teams proactively address potential issues before they become more serious.
  3. Customizing Collection Strategies: ML algorithms can also be used to analyze customer data and identify the most effective collection strategies for each individual customer. For example, some customers may respond better to phone calls, while others prefer email or text messages.
  4. Automating Collections Processes: ML algorithms can automate routine collection tasks, such as sending reminders or following up with customers. This can help collections teams be more efficient and effective while reducing the risk of human error.
  5. Collection Agencies: Determining when to place a past-due debtor account with a third-party collection agency to maximize the chances of recovery. The natural tendency is to delay an agency placement decision and avoid recognizing a loss. Paradoxically, the result of decision avoidance and waiting too long is the bad debt they were trying to avoid. Consequently, companies can benefit from automating placement through ML or even some simple system rules concerning what to do when a receivable reaches X age.
  6. Cash Forecasting: ML can improve financial operations by providing more accurate cash flow forecasting. Traditional AR software solutions typically rely on static assumptions about customer behavior and payment patterns, which can lead to inaccurate cash flow projections. ML algorithms can analyze historical payment data and identify trends and patterns that are likely to continue in the future. This can allow businesses to make more accurate cash flow projections and better plan for future expenses and investments.

Machine learning is a powerful tool for accounts receivable software because it can help collections teams make more informed decisions.

Using Natural Language Processing (NLP) in Accounts Receivable (AR) Software

An enhanced way that ML can improve the AR collection process is by using natural language processing (NLP) technology. NLP technology analyzes unstructured text data, such as emails, PDFs, and remittance backups, to extract meaningful insights.

In this context, NLP technology can analyze customer communications to identify issues preventing them from paying their invoices. For example, NLP algorithms can identify common complaints or issues that customers may be experiencing with the products or services provided. By addressing these issues, businesses can improve customer satisfaction and reduce the likelihood of late or missed payments.

Additionally, NLP technology can automate customer communications, such as sending payment reminders and follow-up emails. By automating these communications, businesses can reduce the time and effort required to follow up with customers manually.

In Summary

In conclusion, machine learning has the potential to revolutionize the way businesses manage their accounts receivable processes. By analyzing large amounts of data and identifying patterns and trends, ML algorithms can provide valuable insights into customer behavior, improve collections, and provide more accurate cash flow projections. As businesses continue to rely on technology to streamline their operations, machine learning in AR software will likely become increasingly common. Machine learning can potentially revolutionize B2B accounts receivable processes, including collections, dispute and deduction management, and invoice collections.


12 Step Program to Collect A/R Faster

Accounts receivable manager conducting proactive collection calls and tracking payment performance metrics.

The Debtor’s Psychology

A debtor figures that if their account is 180-360 days old, they’ll never have to pay it, and certainly not the full amount. Chronic slow-paying customers can be re-trained to be profitable, long-term relationships, but they require constant attention so they do not age out to become bad debts. With a little effort, you can cure customers’ slow payments.

  • Many large companies use software to optimize their Accounts Payable – they track how well you follow up and will pay you accordingly.
  • Small companies follow the same practice without the software – they pay you based on how you train them to pay you.
  1. If you allow customers to pay late, they will pay late, and your cash flow suffers.
  2. Past-due customers will order from your competitors rather than risk your asking them to pay up. Being a nice guy costs you sales.
  3. If you ignore delinquencies too long, they will become your bad debt ex-customers.  You lose both ways.
  4. Debts are 200% more likely to be collected if assigned for collection at 90 days vs. 360 days.

This is a zero-sum game: if you do not collect what you are owed, your customer will pay another vendor who was more aggressive in their collection follow-up. Your customers will learn from your practices. Unfortunately, many companies wait until the customer is far past due before taking action.

Routine Accounts Receivable Collection is a Production Job

Like many repetitive processes, accounts receivable collections is a “production” operation and can be “re-engineered” to improve cash flow, reduce DSO and slash the disputes that result from letting unpaid accounts go stale.

Cash flow is the lifeblood of every business, and success or failure depends largely on how accounts receivable are managed. Collecting receivables more quickly enables you to reduce bank borrowing, invest more in growth, and improve profits. Our experience is that delinquencies can be dramatically reduced – cut in half, or even better with some planning and effort.   Here are some basic ideas to implement in your organization.

1. Credit and Collection Policies

Do not leave it to individuals to decide policies and rules about how frequently the customer should be contacted for money and what the proper collection protocols should be.

Every company needs a credit and collection policy that provides the framework for the job.  Management should develop this policy and detail the criteria and tools to be used (restricting credit, management scalation, collection agencies, etc.). Even a one-page credit and collection policy may be enough if you are a small company. Larger companies need to go into much more detail.

The customer should receive a written explanation of your credit and collection policies, outlining the business rules. Make it part of your Credit Application, but if not, email it afterward so they understand your business rules.

2. Prioritize Your Work

Prioritize collection activity so you are working on the receivables that offer the greatest cash flow payback. If you have an advanced system, you can also employ risk or payment scoring to assign the accounts needing first attention. You may also consider outsourcing all or part of the past-due collection function to a qualified agency, which usually produces more focused and better results and is often less expensive than full-time staff.

3. Collection Performance Standards

Most people do not like to ask for money. Consequently, left to their own devices, they may not call with the consistency required for an effective collection function. Your people need performance standards for monthly cash flow, DSO, delinquency percentages, number of calls and contacts, etc. If you track it, it will get done.

4. Assign Goals and Track Results by Department and Collector

Collections is a “production” job; you need to develop clear goals on cash and delinquency targets for the month and the number of daily calls and contacts (since you need to have all customers touched). Daily reporting should include calls made, promises obtained, disputes resolved, etc. Monthly reporting should roll up the daily results, plus report the financial results – Cash Collected, DSO, Delinquencies, etc. Of course, the department goals must match up against the corporate objectives of your CFO.

5. Credit Application and E-Signatures

Use an automated credit application system incorporating your policies and business rules,  and utilize e-signatures to have an officially signed agreement. This will save you countless hours that you can spend collecting. Sign up with one of the several signature applications, and forget faxes. This accelerates and simplifies signing agreements, including settlement agreements, promises to pay, etc.

6. Collection E-Mail Templates and Collection Call Scripts

How much do you want your staff to set their own rules? It depends on an individual’s experience, but generally, the answer is “little to zero.” Do not leave it up to staff to develop their individual communications standards.

This includes collection letters, voice mail messages, and collection scripts. Standard templates meeting best practices should be developed and used by all. We advise skipping written snail-mail letters, except when you must give official notice, certified mail, etc.

7. Make Paying Easy

Offer your smaller customers multiple ways to pay, including e-check, ACH, and credit cards. 

8. Contact Data

Your customer contact data should always include the email addresses of your payables contact, controller, and management.  If the customer is a small company, you should also have the owner’s cell phone. This information can be added to your new customer credit application. A surprising number of creditors do not have current information on who to contact to resolve collection problems.

9. Systems and Workflow

If you have sizable receivables or many customers or still use spreadsheets, you must consider workflow automation to manage collections and routine tasks. See Carixa for an idea of what a comprehensive, integrated “Software as a Service (SaaS)” system can do for you. You are guaranteed faster collections, lower DSO, fewer delinquencies, and reduced overhead if you deploy powerful collection software. As with all SaaS offerings, it is internet browser-based, so there is no software to install or hardware to purchase.

10. Collection Cycle

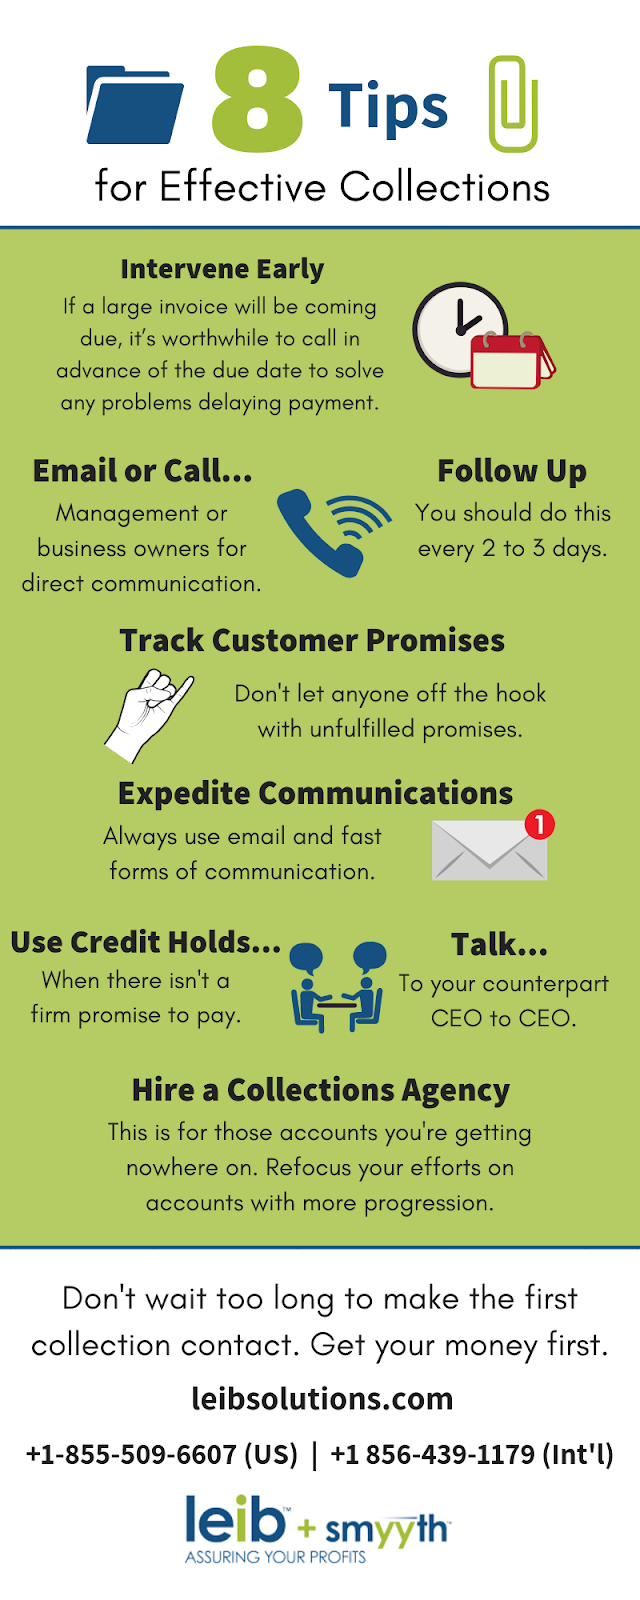
Don’t wait as long as your competitors to make the first collection contact; use email to your advantage. Get the money first through early Intervention. If a large invoice will be coming due, it’s worthwhile to call before the due date to solve any problems delaying payment. And don’t be shy about sending “friendly reminders” at even five days.

  1. If you do not receive a response to a call or email, follow up every two or three days until you get a response.
  2. If your debtor is a smaller company, escalate a more serious collection matter by emailing or calling the business owner.
  3. If collection delinquency is serious (regardless of the size of the customer), call an executive-level person (say, CFO). They do not like receiving these calls and will handle the problem.
  4. Do not take them off the hook with unfulfilled promises. Call if the funds were not received the day they agreed to pay.
  5. Expedite all communications. When sending invoice copies or other documents, scan and email them. Email eliminates the usual excuses, and you are assured that it’s reaching the intended party.
  6. Use credit holds when an account is delinquent without a firm promise to pay.
  7. If you are getting nowhere, assign the account to a collection agency and move on to current accounts receivable.

11. Train Your Staff

A bit of training and role-playing can improve your collection effectiveness dramatically. Outside training, help is worth an investment since the benefits will be long-lasting. This includes the Fair Debt Collections Practices Act. Although the FCPA doesn’t usually apply to B2B transactions, always remember to comply with the FDCPA when dealing with consumers.  Regardless, commercial collections and consumer customers should always be handled professionally and consistently, which reflects your corporate culture, even the few abusive customers.

12. Using Collection Agencies and Outsource Services

Professional receivables organizations such as Leib Solutions offer First and Third-party collection services and are an essential part of receivables management.

  • “First-party” is another name for day-one outsourcing of all receivables under the client’s name. Generally, first-party is performed for a low service fee, often per invoice or a low percentage (even under 1% if your volume is high).
  • “Third-party” is the traditional collection agency service when accounts get old—usually, no collection -no fee.

Uncollected invoices will eventually be written off as bad debts. You should assign them to a qualified collection agency while they are still collectible.

It’s shocking how many companies wait until there is little hope of collection, telephone numbers disconnected, or even bankruptcy before calling a collection agency. This is evidence of a failed collection policy. The old saw that “better to get 75% of something than 100% of nothing” applies here. It’s just common sense.

The first step in improving your company’s cash flow is to take the first step and lay out a plan of attack. If you want some advice, contact us. We will be happy to help in any way we can.


9 Best Collection and Accounts Receivable Metrics

Financial dashboard displaying DSO, ADD, ART, CEI, and deduction KPIs for accounts receivable performance tracking.

Understanding DSO, DDO, and Other Accounts Receivable KPIs

A/R turnover – the credit-to-cash cycle – and working capital are critical to your business, so it is essential to monitor the Key Performance Indicators (KPIs) and other metrics that track your company’s credit, collections, and deduction management health.

In addition, businesses have become more complex, so receivable performance analytics are essential to keep track of the financial health of your receivables.

Here are the key metrics to implement.

1. For Collections, Days Sales Outstanding (DSO) and Best Possible DSO (BPDSO)

Standard DSO is the metric for tracking the effectiveness of Invoice Collection Management. That is, how long it takes to collect payments based on the invoice date, intending to reduce your DSO to as close as possible to your average terms of sale (the “Best Possible DSO” or “Best DSO”). Depending on the industry and seasonality, DSO calculations can get complicated.

However, for a simple example, suppose that your AR totals $1,600,000, and Credit Sales for the last twelve months were $10,200,000. The formula would be:

DSO = Total A/R ÷ Total Credit Sales X 365, and the answer a DSO of 57.2 days.

Best Possible DSO uses only your current (not yet past due) receivables and tells you what your best “on-time payment” turnaround could be.

Best Possible DSO = Current A/R ÷ Total Credit Sales x 365. Using the above numbers, if your Current A/R is $800,000, your Best Possible DSO comes out to 28.

In this case, you have a lot of potential for improvement between the Standard DSO of 57 Days and the Best Possible DSO of 28.

Working towards a DSO that is as close as possible to your Best Possible DSO should be the goal of your department to have a healthy cash flow and ensure your AR management is as efficient as possible.

Once you start calculating the DSO and Best DSO, create monthly targets that “move towards” the Best DSO. You’ll unlikely achieve perfection, so make strides to reduce the metric over 3-6 months.

2. Average Days Delinquent (ADD)

ADD is how many days on average payments are overdue and can be a warning sign of problems. If the number is high, you must determine whether your systems, collections, and invoice processes need improvement. ADD is calculated as the DSO minus your actual (average) terms.

For example, with the hypothetical company above in #1, the ADD would be ten days on September 30. However, say one year later, the ADD is 15 days. That may mean your processes may be falling behind.

Over time, measuring ADD and DSO will show whether you are improving, static, or falling behind.

3. Accounts Receivable Turnover Ratio (ART)

ART measures how effectively you collect your revenues as an annual broad benchmark. It is determined by taking your net credit sales and dividing it by your average accounts receivable balance. When the ratio is higher, you turn A/R into cash more quickly, thus improving your working capital, cash flow, and liquidity.

A low ratio can mean it is time to reconsider credit and collection procedures and add collection automation.

The calculation is ART = net credit sales ÷ average accounts receivable. Using an example of $15,000,000 sales per year ÷ average AR of $2,200,000 = 6.8 ART or, in another case, $15,000,000 sales ÷ average AR of $3,200,000 = 4.7 ART (worse).

4. Collection Effectiveness Index (CEI)

While ART measures how often accounts receivable turn over, CEI measures how effectively you collect all outstanding money in a specific period (usually measured over one year). CEI is calculated as CEI = (beginning A/R + monthly credit sales – ending total A/R) ÷ (all beginning receivables + monthly credit sales – ending current receivables) x 100.

5. Deduction Days Outstanding (DDO)

By dollars: Track Customer Deduction Management results separately from invoice collection, using Deduction Days Outstdanind as the KPI. Similar to how you calculate Days Sales Outstanding (DSO) for invoice collections, add the average daily deductions amounts received during a period (say 90 days), and divide the total outstanding deductions by the average per day. For example, if deductions at the end of a month total $1,000,000 and you receive an average of $25,000 per day, the DDO = 40 days.

By the number of deductions: Another way to think about DDO is to use the number of unresolved deductions since the usual DDO metric often looks better than it is because of the operational focus on large dollar items. Using this method, if deductions at month-end total 6,000 items and you receive an average of 100 deductions daily, the DDO = 60 days.

6. Deduction Effectiveness Index (DEI) New

The A/R department spends so much labor and expense (often 75% of the A/R resources) in deduction management to discover the root causes of errors, find the improper deductions, and ultimately get your money back. 

We employ what we named the DEI metric as a critical KPI to track how we are doing. To determine the DEI every month, compare the total deductions vs. those found to be incorrect vs. the collected deductions. Do this by category (returns, shortages, discounts, trade promotions, etc.) and track your company’s progress.

Unfortunately, industry-peer data is not helpful as company processes and policies differ. Hence, the best way to measure your success is to set internal baselines (where you are today) and work to improve from there.

Regular undisputed invoice receivables have an accepted metric of what percentage you should collect (i.e., 100% minus bad debts). For deductions, however, there is no objective metric for the rate you should recover.

Therefore, an excellent way to determine if you are leaving profits on the table is to have unresolved customer deductions post-audited by an outside firm before writing them off.

7. Number of Invoicing Disputes

Mistakes are costly, so you should track, by reason, how many invoices have to be revised or credits issued due to billing or process errors. If the number is trending upward, it could mean that you have systemic problems in order entry, invoicing, or fulfillment, all of which will impact DSO and company profits.

8. Bad Debts to Sales Ratio

Measure bad debts as a percentage of revenues, but always look behind the number if you can and compare the credit losses against sales (i) gained due to more lax credit risk policies or (ii) lost due to overly restrictive corporate credit policies. Most high-risk credit decisions are intentional and logically decided, calculating that the extra revenues will offset potential losses.

9. Percentage of High-Risk Accounts

Doing business with high-risk customers is part of a business strategy. Do you have an excess of depreciating inventory? Do you need extra market penetration in a territory? Many industries are inherently “high-risk,” so the credit and sales managers are aligned and have to do what they can to offset the additional risk via credit instruments and, perhaps, terms or pricing.

Final Thoughts: How do you manage accounts receivable if you don’t measure receivable performance?

Monitoring your accounts receivable metrics and KPIs is essential to running a healthy business. You’ve collected valuable statistics and need to see how you measure up.

First, of course, you’ll need to look at the historical performance within your organization, but that’s not enough. You also need to compare your performance to industry peers. With these comparisons, you can share insights with Finance, Sales, and Marketing.

You must be on top of your game in today’s global, highly competitive economy. This post was written by the consultants at the Smyyth group of companies.

Collection Best Practices That Increase Cash Flow

Collections team using structured call scripts and AR workflow software to reduce DSO and improve cash flow.

Accounts receivable commercial collections at many companies are still in the green eyeshade era with out-of-date processes, leaving many opportunities to improve results. However, like many repetitive processes, collections is a production operation and can be engineered to improve cash flow, reduce DSO, and slash the disputes that result from letting unpaid accounts go stale.

This is a zero-sum game. If you do not aggressively work to collect your receivables, the customer will pay other vendors who were more assertive in their collection follow-up. Your customers learn from your practices. Unfortunately, many creditors wait until the customer is seriously past due before making the first collection contact. 

At Leib Solutions, considered one of the best commercial collection agencies, we know cash flow is the lifeblood of every business, and success or failure depends mainly on how well accounts receivable is managed. Collecting receivables more quickly enables companies to reduce bank borrowing, invest more in growth, and improve profits. Our experience is that delinquent A/R can be dramatically reduced, even cut in half. Here are some basic ideas to implement in your organization:

  1. Credit and Collection Policy. Every company needs a credit and collection policy that gives the department the appropriate framework to work. This policy (and procedures) should be by management – detailing the criteria, parameters and tools used (restricting credit, collection agencies, lawyers, etc.). Even a one-page credit and collection policy may be enough for a small company. Larger companies need to go into much more detail.
  2. Advise the Customer of Your Policies. The customer should receive a written explanation of your credit and collection policies- how you expect them to behave. Ideally, make it part of your Credit Application, but always email it afterward, so they understand the business rules.
  3. Credit Application. Use a credit application which includes your policies and purchase terms, and use e-signatures to have an official, signed record. The buyer invariably has their terms on the back of their purchase order, which will not be favorable to the seller, so it is common sense to establish your business rules upfront and get it signed.
  4. Contact Data. Your customer contact data should always include the telephone and email addresses of your payables contact, controller, and customer management. You should also have the owner’s cell phone number if the customer is small. All of this information should be on your customer credit application. 
  5. E-signatures. If you need documents signed, such as settlements and promises to pay, use e-signatures and forget faxes. Digital signing is effortless and is legally binding. It simplifies getting any agreements signed.
  6. Correct Your Customers’ Habits. Large customers use software to optimize their accounts payable: they track how soon and persistently you follow up and pay you accordingly. Small companies follow the same practice without the software, often waiting until you call. They pay you based on how you train them to pay you through your everyday collection practices.
  7. Set Up Standard Procedures and Train Staff. Do not leave it up to collectors to make up their own policies and rules about how soon or frequently the customer should be contacted. Most people do not like to ask for money; without rules, they may not call with the consistency required for effective collection results.
  8. Letter Templates and Call Scripts. How much do you want your staff to exercise their inner artist? Do not leave it up to staffers to make it up as they go along or to develop personal collection strategies. Establish the rules, and provide standard collection letter or email templates and scripts for telephone and voice mail. Email vs. letters? There is no contest, as email is immediate and less work, but just as with form letters, you need to use pre-formatted collection emails.
  9. Prioritize Your Work. Even with experienced collection staff, you need to prioritize collection activity so your staff works the receivables that offer the most significant cash flow payback. If you have an advanced system, you can also employ risk or payment scoring to assign the accounts needing first attention. You may also consider outsourcing all or part of the function to a qualified agency, which usually produces more focused, better results and usually at less expense than full-time staff.
  10. Assign Goals and Track Results by Department and Collector. Collections is “production” work, and you need to develop clear goals for monthly cash and delinquency targets and the number of daily calls and contacts (since you need to have all customers touched).
  11. Reporting. Daily reporting should include calls made, promises obtained, disputes resolved, etc. Monthly reporting should roll up the daily results, plus report the financial results – Cash Collected, DSO, Delinquencies, etc. Of course, the department goals must match up against the corporate objectives of your CFO.
  12. Make Paying Easy. Offer multiple ways to pay, including ACH and credit card, with your smaller customers. Intuit QuickBooks, among many, has a very effective and free ACH offering for e-billing and a payment module that integrates with QuickBooks.
  13. Systems and Workflow. If you have sizable receivables outstanding or many customers, or if you still use spreadsheets, you must acquire an A/R workflow system to manage collections and automate routine tasks. See Carixa for an idea of what a comprehensive, integrated “Software as a Service (SaaS)” system can do for you. Deploying this powerful collection software guarantees faster collections, lower DSO, and fewer delinquencies. As with all SaaS offerings, it is internet browser-based, so there is no software to install or hardware to purchase.
  14. FDCPA Regulations. The Fair Debt Collections Practices Act doesn’t apply to B2B transactions, but always keep in mind that you must comply with the FDCPA if you are dealing with consumers. Regardless, all customers should always be handled professionally and consistently, which reflects your corporate culture, even the few abusive customers.
  15. Collection Activity Cycle. Don’t wait as long as your competitors to make the first collection contact; use email to your advantage. Get the money first. Here’s an infographic with eight tips on what you should do to maximize your returns in the collection activity cycle:


Outside Help: Collection Agencies and Outsource Services

Professional receivables organizations such as Leib Solutions or Smyyth.com offers both First-party and Third-party collection services. First-party is another name for customer service-oriented outsourcing of non-seriously delinquent receivables under the client’s name. Generally, first-party services are performed for a low account service fee or a low percentage fee. 

Third-party collections are the traditional “collection agency” services when accounts are old and uncooperative, with fees commensurate with the age of the receivable. 

Some creditors wait until there is little hope of collection, telephones disconnected, or bankruptcy before calling a qualified collection agency. This delay is evidence of failed collection management. Often the company is concerned about collection fees, but the old saw “better to get 70% of something than 100% of nothing” applies here. It’s just common sense.

The first step in improving your company’s cash flow is to take the first step. Lay out a plan of attack, or, if you want some advice, contact us. We will be happy to help in any way we can.

Leib Receives Coveted A.M. Best “Expert” Award for the 15th Year

We are proud to announce that A.M. Best has, for the 15th straight year,  selected Leib Solutions as one of a handful of companies in the world receiving the coveted “Expert Service Provider” designation awarded for business debt collection and accounts receivable services.

Leib Solutions has been in the commercial collection industry for over 40 years and is an expert at business debt collection in the insurance, manufacturing, distribution, services, and technology industries. Leib is affiliated with the Smyyth group of companies, which specializes in advanced SaaS software and outsourcing services for accounts receivable, credit, collection, and A/R deduction management. The organizations have decades of expertise and leading-edge automation to help clients optimize cash flow and reduce losses due to A//R revenue leakage.


Digital Signatures in Credit and Collections – A Best Practice

A digital signature is a cryptographic technique to provide authenticity, integrity, and non-repudiation of electronic documents or data. It is essentially an electronic version of a handwritten signature that provides assurance that the document or message has not been altered and was indeed signed by the claimed sender.

A digital signature is created using a combination of public and private keys. The sender uses their private key to sign the message, and the receiver uses the sender’s public key to verify the signature. This process ensures that only the intended recipient can read the message and that the sender cannot deny signing it.

Digital signatures are commonly used in industries such as banking, healthcare, legal, and government sectors to authenticate electronic transactions, contracts, and other important documents.

Business Case for Digital Signatures in Credit and Collections

Use digital signatures to streamline and speed up credit and collection agreements. Some are still uncertain whether electronic signatures are binding in the United States and Globally,  but the use of e-signatures has become routine and is valid for most transactions. The following information is provided from U.S Government websites and our Smyyth companies’ corporate e-signature policies.

E-signatures have eliminated the hassle of completing commercial transactions, including use in Credit Applications and credit and collection agreements, to an extent that going back to faxes and emailed documents would be unthinkable for routine transactions. If your company is considering new credit risk software, collection software, or AR management software, consider including e-signatures in your processes. You should include all the standard company forms as templates within the digital signature system you decide on. Collection agencies also routinely use digital signing to confirm debt payment plans, as well as for creditor agreements.

The legality of Digital Signatures

Electronic Signatures in Global and National Commerce Act (E-Sign Act) and The Electronic Signatures in Global and National Commerce Act (E-Sign Act signed into law on June 30, 2000, provide a general rule of validity for electronic records and signatures for transactions in or affecting interstate or foreign commerce. There are four basic parts required for an electronic signature to be recognized.

  1. The parties must intend to sign, just as with any written contract.
  2. The parties must agree to do business electronically. For businesses, this can be shown by the circumstances of the interaction. Consumers, however, must affirmatively consent to use electronic records and receive related consent disclosures.
  3. The e-signature system must capture and keep the record that reflects the process by which the “signature” was created or generate a graphical or textual statement proving it was executed.
  4. The United States Laws require that the e-signature records be capable of retention and reproduction by the parties.

The E-SIGN Act solidified the use of electronic records and electronic signatures in commerce by confirming that electronic records and signatures carry the same weight and have the same legal effect as traditional paper documents and wet ink signatures. Both laws provide the following:

  • No contract, signature, or record shall be denied legal effect solely because it is electronic.
  • A contract relating to a transaction cannot be denied legal effect solely because an electronic signature or record was used in its formation.

Note: We do not provide legal advice, and we always recommend you consult with your counsel if you have any concerns. Also, many countries have specified certain types of documents or that are not appropriate for e-signatures, including wills and trusts, powers of attorney, and declarations under oath.

Credit and Collection Scoring Best Practices

There are numerous reasons to use automated credit scoring in your credit (and collection) operations, including faster and better quality decisions, enhanced customer service, more effective compliance and controls, and significantly reduced overhead. Employing credit scoring in a B2B environment is credit management  “Best Practice,” especially if you have many customers.

Using Smyyth’s Carixa cloud technology for credit-to-cash management, Leib can seamlessly incorporate Credit2B’s advanced scoring results into Carixa’s enterprise credit management workflow. Leib and Credit2b.com are Smyyth affiliates.

Here are some benefits to consider from credit scoring, which includes leveraging your own historical data,  credit bureau business information, and industry trade payments.

7  Good Reasons to Use Credit and Collection Scoring

  1. Speed of Credit Decisions. Scoring can dramatically shorten the time it takes to approve orders, a major customer service and sales benefit.
  2. Prioritized Collections.  Use blended credit risk scores to set collection priorities, ensuring the accounts with the highest risk for non-payment get collection attention first. If you focus on “risk,” not just age and value, you will have better outcomes and less bad debt.
  3. Personnel and Overhead Savings. Scoring automates the decision process, dramatically cutting down the personnel costs associated with credit approvals and letting you do more with less.
  4. Credit and Collection Policy. You can use credit and payment scores to establish corporate policies for risk and slow payment tolerance. Credit and Payment scoring ensures consistency for applying  credit policy.
  5.  Collection Agency placement based on the account age rules eliminates “decision freeze” when deciding when an account is turned over to a bad debt collection agency, reducing write-offs.
  6. Customer Advisory. The credit manager can become a partner to sales if you counsel customers on how they can improve their scores by highlighting areas of weakness.
  7. Fewer Bad Debts. You can expect reduced bad debts using a valid scoring methodology since many smaller customers would not get the same level of manual review as the larger exposures.

Data Elements Used in Automated Scoring

Financial metrics for large corporations can be predictive in the 2-5-year range, and many credit analysts still use a traditional or modified Altman-Z Score for this purpose. However, financials are often not available for smaller customers or they are often stale, unreliable, and subject to fast swings. For these smaller debtors, other data elements become more critical, including:

  1. Years in business
  2. Experience of principals
  3. Number of employees
  4. Revenue and Assets
  5. Business and Industry Trends
  6. Financial information (if available) using a dozen key metrics
  7. Public records information
  8. Supplier payment experience (including your trade credit groups)
  9. Bank and Lender Experience
  10. Credit Line Utilization
  11. Credit exposures of other industry suppliers
  12. Public filings, liens, etc.
  13. Transparency with key suppliers
  14. Derogatory comments; Reputation

Using Big Data and Machine Learning

Building truly predictive credit scoring is now significantly easier with the ability to capture “Big Data” from multiple sources and analyze it with powerful software and hardware, where the “machine” can learn from experience and adjust its conclusions; that is, make and correct its decisions based on experience, patterns and trends it sees in the data. 

This is called “Machine Learning,” where computers are taught to detect patterns in data to both predict and validate outcomes with regression testing of past events and then adjust those based on current events. Reaching this goal has gotten much easier due to the rapidly increasing power of computer processing.

W.E. Deming famously said said, “Without data, you’re just another person with an opinion.”

We would add, “if you can’t process the data to produce real insights, they’re just numbers.”

Our experience is that leveraging machine learning can significantly improve predictive credit and payment scoring. We use these techniques to build and customize automated credit scores and credit lines for large trade creditors that need to improve and accelerate credit decisions. As we are a cloud-based service,  there is no software to buy, and we integrate easily with client processes and systems.

Designing a Scoring Model

Our Credit Scoring Framework has a Simple Flow:

  1. Working with a technology provider like Carixa, decide on the outcomes you would like to predict (e.g., bankruptcy, default, severe delinquency, or X days late), and establish a model.
  2. Create a training sandbox using data attributes from multiple sources, including your own experience; for example, business standing, financials, and debtor payment histories, often as many as a dozen separate data elements, and even unstructured credit data, such as industry “attitudes.”   Sharing this in our cloud platform speeds up adjustments, saves time, and simplifies managing the data.
  3. Adjust for the outcome you are aiming for or test multiple outcomes based on “model training sets” created in your sandbox and adjust the importance or weight of certain elements.
  4. More elements do not always better produce a better outcome; what is important is to pick and test for the right elements. For very small businesses, factors such as years in business, number of employees, and social reputation are critical. Economic factors are important. If the consumer economy turns down, it is a leading indicator of problems with payments and defaults in subsequent quarters.
  5. Machine regression picks and weight-adjusts the credit attributes that are critical for the outcome you are trying to predict in real-time.
  6. Using real-time industry data ensures continuous updates to scoring attributes and weights.

    Advantages
    : The scoring model should self-adjust continuously without manual updates, pulling in more data types than traditional models, including micro and macroeconomic variables, to target the prediction of outcomes that match your company’s needs. The models adjust for specific industry or business needs based on your unique data or information, defining your preferred outcome with great precision.
    To complete a fully automated process, we provide calculated credit lines that can be integrated with any financial or ERP you use.

    Customized Calculated Credit Lines

  • By applying your corporate policies, we can calculate a Dollar Credit Line for you, adjusted to your circumstances. This takes into consideration a number of factors, including your tolerance for risk (are you in a fast growth or more risk-averse environment), lender or insurance limits, or product profit margins (a consumer good with a 60% gross margin will tolerate more risk than a service with a 17% margin).
  • Our modelers interpret your process and policy, replicating your rules in a computer model. By way of example, where no financials are available and the customer has fewer than ten employees, you may decide “do not calculate a credit line” but instead perform a manual review or adjust a CCL based on the presence or absence or magnitude of certain elements.
  • Through feedback through a regressive “fit test,” we can adjust the algorithms as required to bring your scores in line with your desired outcomes.

Advantages: Custom Calculated Credit Lines are built to your circumstances and adjusted as required by your rules, policies, and internal and external events. Machine-generated credit lines are useful for accelerated decisions and risk analysis across an entire portfolio. We can actually do this across 99% of registered businesses in North America.


Summary: By using computational power and a scientific approach to data analysis, you can produce extraordinary results with automated credit decision processing and, in doing so, improve credit decisions and customer service while streamlining credit operations.

Commercial Vs Consumer Collection Agencies

If you are in business, there will come a time when you need to enlist the services of a collection agency to help recover your past-due receivables and bad debts. So how do you find the right one?

Commercial debt usually involves significant amounts and often complex circumstances that can lead to financial issues for your business. If the money owed is business debt, Leib Solutions is a highly-rated expert who handles business-to-business bad debt collection.

What is Commercial Bad Debt?


Commercial or business, bad debt is the result of a company (the debtor) that buys services or products on credit terms but fails to pay what is due to the seller (the creditor). As a result, the creditor must then act by suing the debtor or assigning the account to a collection agency to avoid a loss. In the worst scenario, if the creditor does not take quick action, the creditor has to write off the sale as a bad debt. Usually, the two businesses have a binding written agreement, such as a contract or a purchase order.

Corporate Form and Owner Liability

Typically, business debts are the responsibility of the debtor corporate entity and not the liability of the entity’s owners. The corporate (corp. or inc.) and limited liability company (LLC) forms of organization are intended to protect the owners from the business’s debts. Limited partnerships (LPs) also offer protection, although the “general partner” of the LP may be liable for the LPs liabilities. In Partnerships and Sole Proprietorships, the partners or owners are generally personally responsible, so many business people shy away from these forms of organization.

Collateral and Personal Guaranty

When a corporation’s or LLC’s credit is insufficient, a creditor may request a personal guaranty or cross-corporate guarantees from affiliated companies, in which case those parties are also liable. In cases of long-term credit, the creditor will request collateral, such as property or equipment. Having collateral or a personal guaranty is a powerful inducement to pay.

What is Consumer Debt?

Consumer Debt is money owed by a natural person or persons. Consumer debt collectors usually deal with only one person – the debtor – and the debts are usually quite simple, unlike business debts, which can be much more complex. The collection of consumer debt is a very highly regulated activity. See FDCPA Below.

The Fair Debt Collection Practices Act [FDCPA]

The Fair Debt Collection Practices Act protects consumers from unscrupulous collectors looking to use any means possible to collect the debt and penalize those beyond established ethical guidelines. In addition to the FDCPA, many states have enacted versions mirroring the FDCPA, and others go far beyond with even more protection for consumers.

The FDCPA does not regulate Commercial collection agencies. The debt is still commercial if the agreement with your business customer also includes a personal guarantee. A commercial collection agency would be the appropriate entity to place this account for collection since they have special expertise in dealing with businesses and handling these complex matters.

Collection Agency Credentials

While most State and Municipal laws require licensing of consumer collection agencies for each state in which they operate, many State licenses for commercial collection agencies are reciprocal throughout the United States.

Professional commercial collection agencies also follow the ethical guidelines of trade organizations, including the International Association of Commercial Collectors, Inc. (IACC). Membership in the IACC requires compliance with high standards of practice.

Choosing the Best Commercial Debt Collection Agency

When choosing a commercial debt collection agency, you will be concerned about how long they have been in business, their capacity to act quickly and expertly to collect your money, as well as how professionally they deal with debtors since the agency is a reflection of your company.

You also want to ensure your receivables are given the most professional attention. Using an agency that only handles commercial accounts, and understands the types of disputes that occur in business transactions, will ensure the best results. Commercial collection specialization delivers better results for you.

Unlike consumer collections, the best commercial collection agencies are not “dialing for dollar” call center operations. Instead, they employ business and negotiation experts familiar with your business.

Comments on Collection Agency Fees

Never choose a collection agency because of the lowest collection rates, just as you wouldn’t choose a doctor on that criteria. It’s the expected net results -the amount of money you get back – that are important. A professional agency should always do its best, but keep in mind that the fee percentage they keep is their incentive.